



 Continue with Google
What the Estate tab shows
The Estate tab estimates what is left for your heirs when your plan ends: everything you still own in the plan's last month, less the income tax your heirs will owe on it, the cost of selling property and of settling the estate, and anything you leave to charity. It uses the same projection as the Dashboard and redraws after every change. Planner+
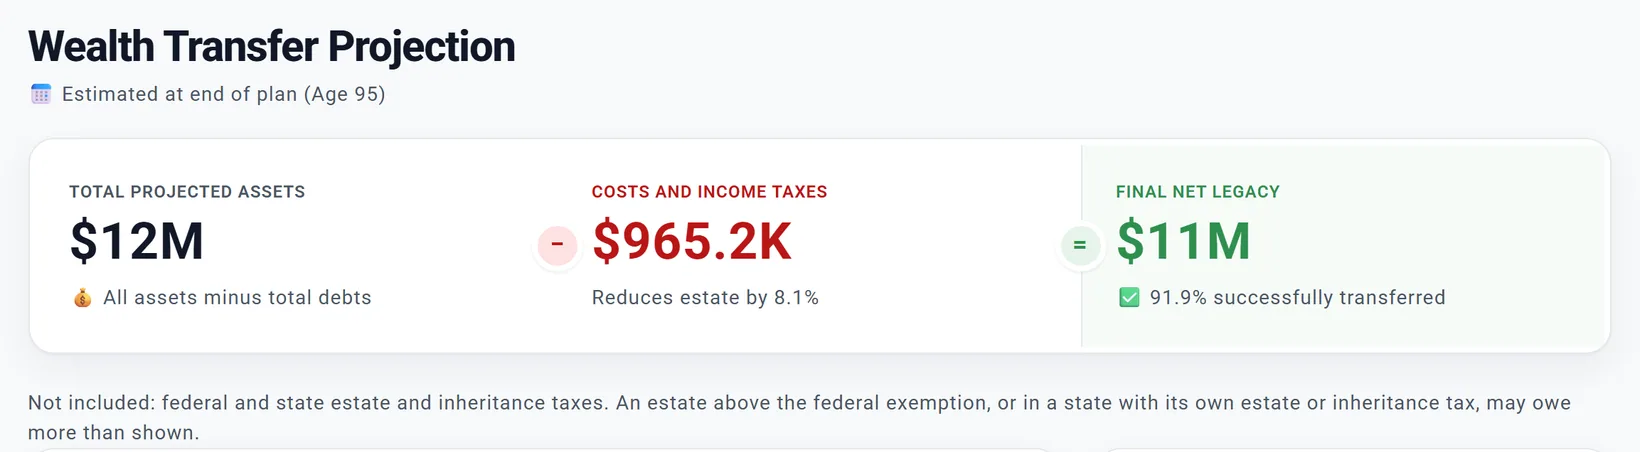
- One moment: the end of the plan, the Primary's Plan End (age 95 for Chris). If your spouse has a later Plan End of their own, it is the spouse's age instead, for example "(age 97 for Jamie)". The tab does not show a first death: for that, see After one of you dies.
- Future dollars: every figure is in the dollars of that year. The Today's / Future dollars switch does not change this tab.
- The Manual projection: one run of your plan with its set returns, never a Chance of Success average.
The starting figure, Total Projected Assets, is your plan's net worth in its last month (the same figure the Summary and the Net Worth chart reach): Chris and Jamie's $11,956,035 at 95.
How to open it
Choose Estate in the top bar, or in the menu on the left. The Plan completeness card on the Summary tab also links to it as an optional detail.

The three figures at the top
- Total Projected Assets: all you own at the end, less your debts.
- Costs and Income Taxes: the income tax on pre-tax money, capital gains tax if you turn step-up off, the cost of selling property and the cost of settling the estate. The line under it is that total as a share of the estate. With Charitable Giving set, it includes the gift and reads Costs, Income Taxes and Charity.
- Final Net Legacy: what your heirs receive, and that as a share of the estate.
For Chris and Jamie: $11,956,035 less $965,217 (8.1%) leaves $10,990,818 (91.9%). The cards round them to $12M, $965.2K and $11M; the ledger below shows the exact figures.
The flow chart
Wealth Distribution Flow follows the money from left to right: the Gross Estate, then each kind of asset (Tax-Deferred, Tax-Free / Roth, Taxable, Cash, Real Assets, and Other Assets or Life Insurance when you have them), then where each goes: To Heirs, or a cost such as Income Tax, Liquidation, Admin Costs or Charitable Giving.
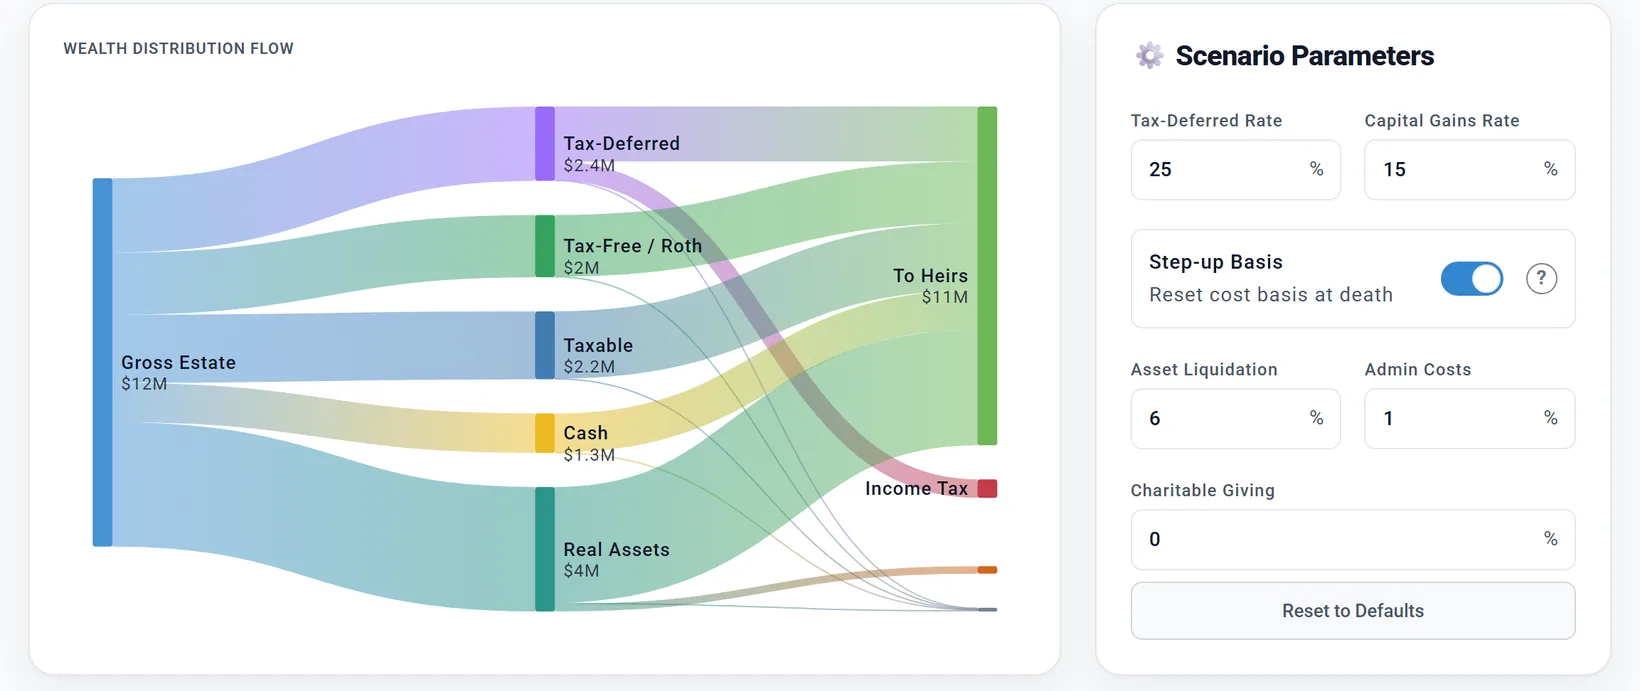
- A band too thin to label has no name on the chart: rest the mouse on it to see what it is and how much.
- Once you set up beneficiaries, To Heirs is split into one band for each of them (see Beneficiaries).
The Asset & Cost Ledger
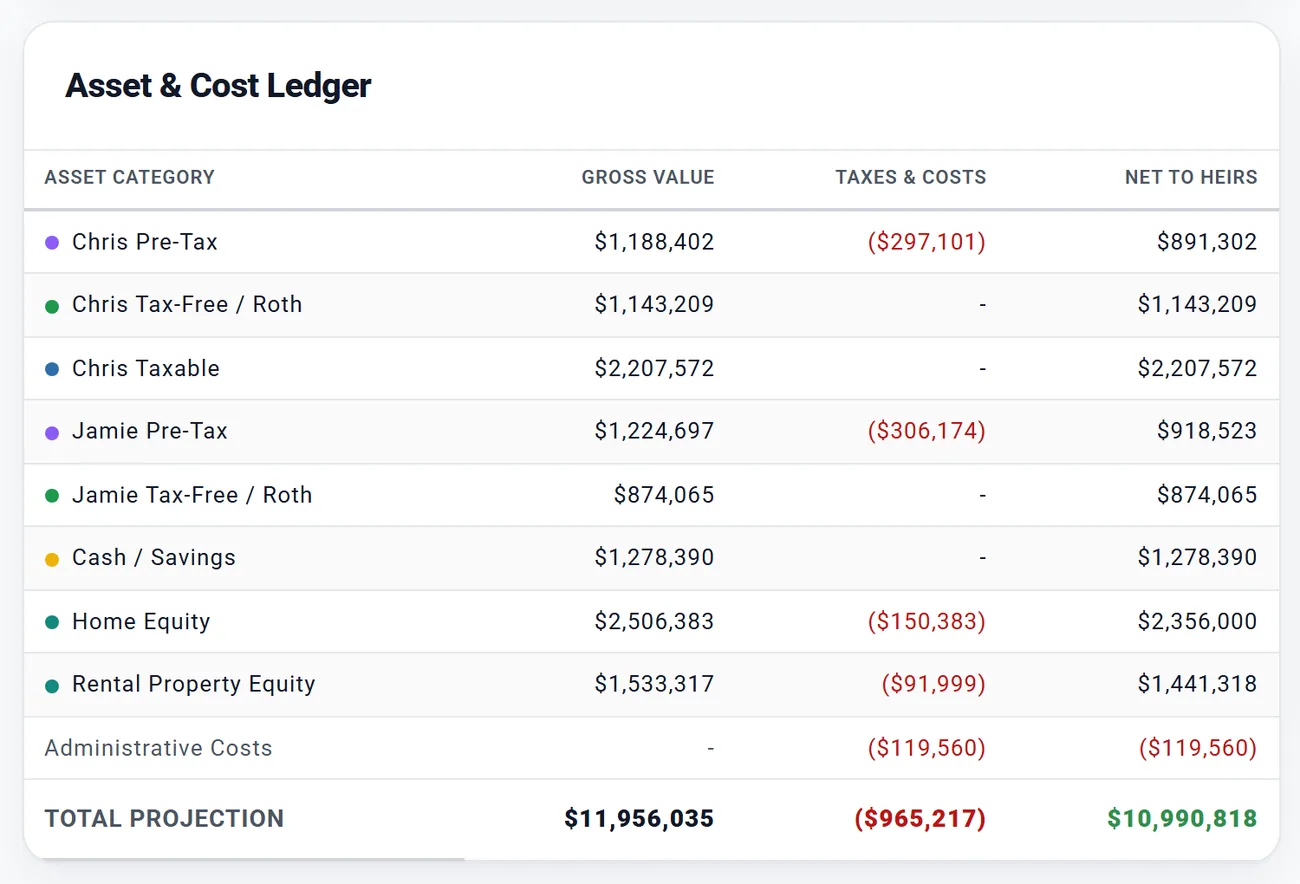
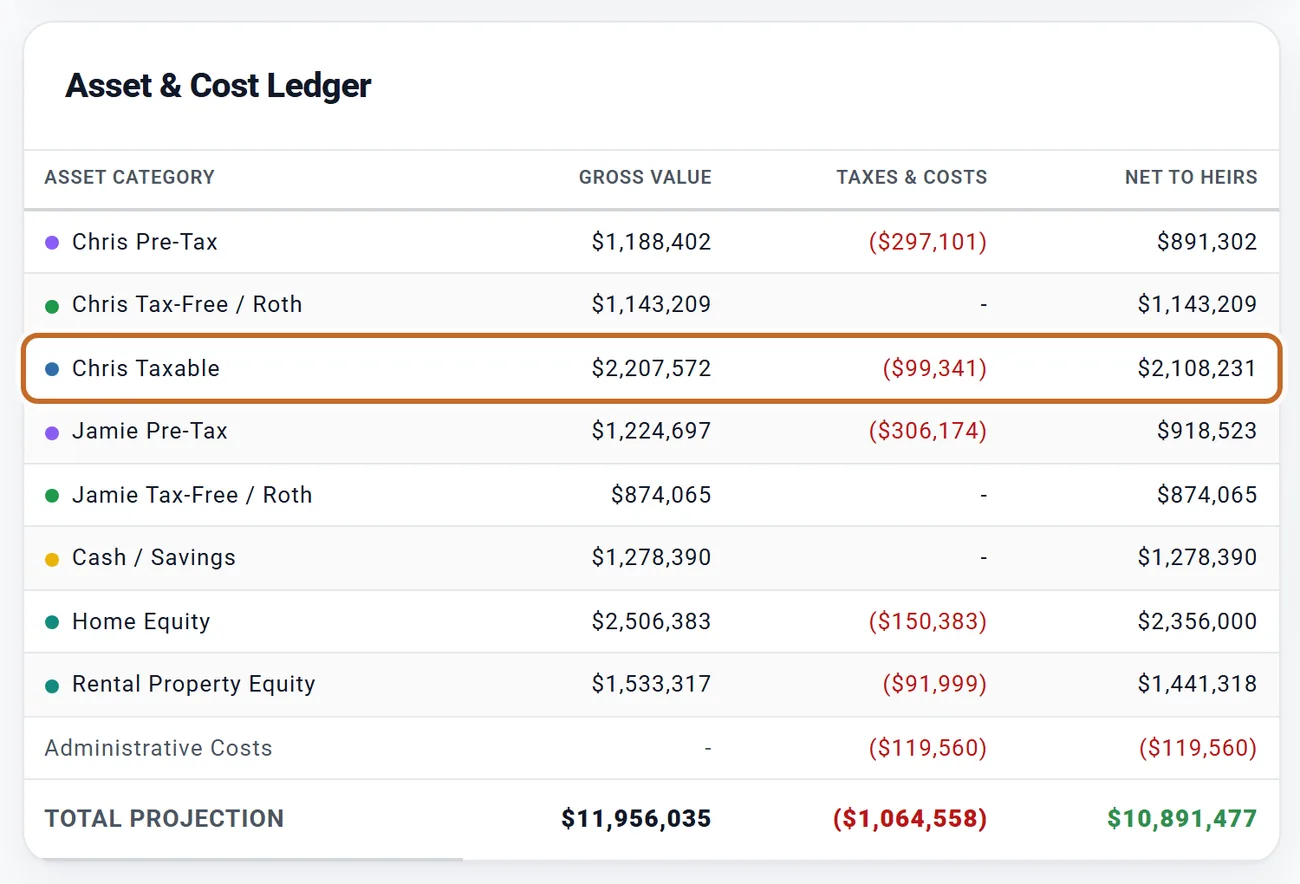
The Asset & Cost Ledger lists each part of the estate with its Gross Value, its Taxes & Costs and what is left, Net to Heirs. Total Projection at the bottom adds them up.
- Investment accounts are one row per person and kind, such as "Chris Pre-Tax" or "Jamie Tax-Free / Roth", not one row per account. An HSA has its own row, and an inherited IRA you still hold shows as "Chris Inherited Pre-Tax" or "Chris Inherited Roth".
- Home Equity and Rental Property Equity are the values less the mortgages linked to them. A loan that is not linked to a property, such as a car loan, is its own negative row.
- Administrative Costs is a row of its own.
- Rest the mouse on an amount in Taxes & Costs to see what it is made of, for example "Income Tax: $297,101".
What each kind of asset costs your heirs
| Asset | What the tab takes off | Chris and Jamie at 95 |
|---|---|---|
| Pre-tax money: IRAs, 401(k)s, inherited IRAs, an HSA, deferred compensation not yet paid | Income tax at the Tax-Deferred Rate (25%) on the whole balance. Your heirs pay income tax as they take it out. | $1,188,402 x 25% = $297,101 for Chris, $306,174 for Jamie |
| Roth accounts and cash | Nothing. | $2,017,274 of Roth, $1,278,390 of cash, in full |
| Taxable accounts (brokerage) | Nothing while Step-up Basis is on. Off: the Capital Gains Rate on the part that is gains. | $0 (off: $99,341) |
| Home and rental equity, other assets | Asset Liquidation (6%), the cost of selling them. | $150,383 on the home, $91,999 on the rental |
| The whole estate | Admin Costs (1%), settling the estate. | $119,560 |
| Life insurance still in force | Nothing: the death benefit counts in full. A policy owned by a trust is listed with "outside the estate" and left out of every total. | None in this plan |
- The tab applies one rate to all your pre-tax money at the end. It does not spread your heirs' tax over the ten years most heirs have to empty an inherited IRA, or use their own tax brackets: set the Tax-Deferred Rate to the rate you expect them to pay.
- An HSA counts as pre-tax because an heir who is not your spouse pays income tax on all of it.
- With step-up off, the gains are the share set as Taxable Gains (%) in the Taxes box (30% to start with): $2,207,572 x 30% x 15% = $99,341.
For what happens to an IRA you inherit yourself, see An inherited IRA on the accounts page.
Scenario Parameters
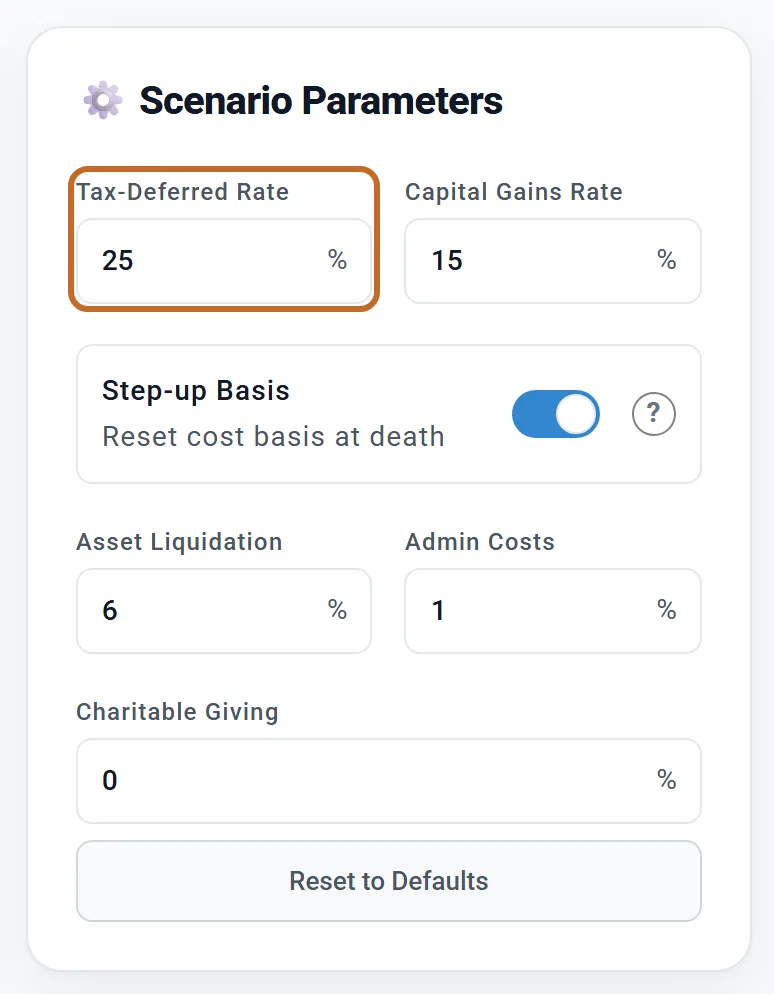
The Scenario Parameters panel holds the rates the tab uses. Type a whole percent; the tab redraws at once.
- Tax-Deferred Rate (25%): the income tax your heirs pay on pre-tax money.
- Capital Gains Rate (15%): used only with step-up off.
- Step-up Basis (on): "Reset cost basis at death". The "?" beside it explains it (below).
- Asset Liquidation (6%) and Admin Costs (1%).
- Charitable Giving (0%): see Leaving part to charity.
- Reset to Defaults puts every rate back.
These rates are saved with the plan you have open, so each plan can have its own. They change no other part of the projection.
The Tax-Deferred Rate counts in the Optimizer too
The Optimizer, the Roth strategy's AFTER-TAX ESTATE card and the Withdrawal Planner's Find the best option all value pre-tax money left at the end after this same rate, and their cards name it: "pre-tax money counted after an estimated 25% tax, your Estate tab assumption". Set it to 32% here and they count it at 32%. On the Estate tab itself, 32% takes Chris and Jamie's legacy from $10,990,818 to $10,821,901. See what the Optimizer looks for and what a Roth strategy is worth.
Step-up Basis
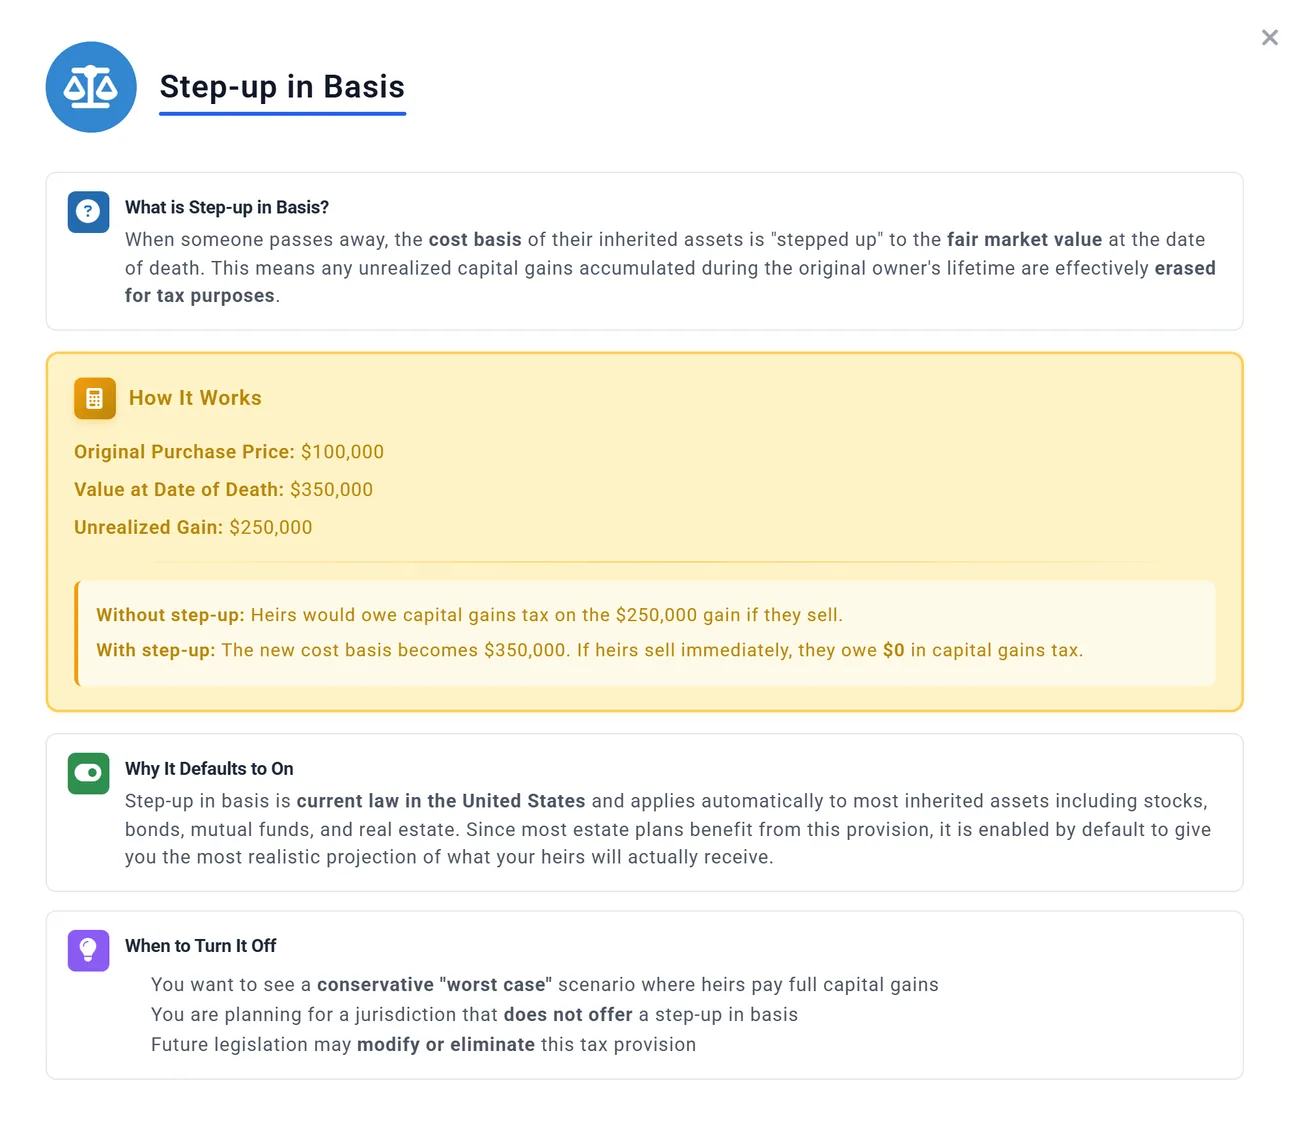
Under US law, what your heirs inherit takes its value on the day of death as its cost, so the gains it built up while you owned it are not taxed. That is why the switch starts on, and taxable accounts lose nothing.
Turn it off to see a cautious case where your heirs pay capital gains tax as well: Chris's taxable row then loses $99,341, and the tab's costs rise from $965,217 to $1,064,558.
Leaving part to charity
Charitable Giving sets a share of the estate that goes to charity. The tab takes it from pre-tax money first (then taxable accounts, property, cash, and Roth money last), because pre-tax money is what your heirs would pay income tax on. So the gift also cuts the income tax.
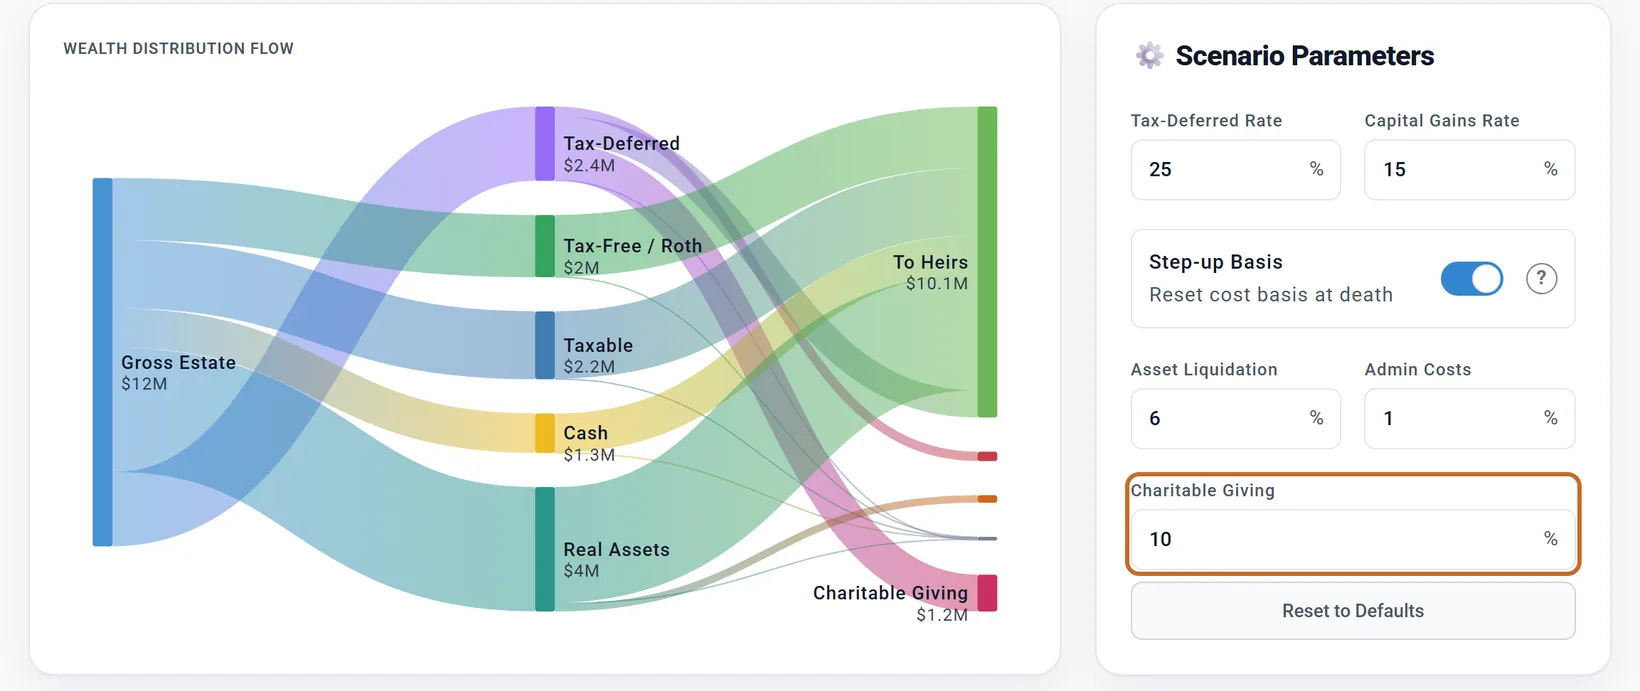
For Chris and Jamie, 10% sends $1,195,604 to charity, all of it from their pre-tax accounts; the income tax drops from $603,275 to $304,374 and Final Net Legacy is $10,094,115. With a gift the middle figure at the top becomes Costs, Income Taxes and Charity, and the gift also shows in the ledger's Taxes & Costs column and in the flow chart.
Key Takeaways
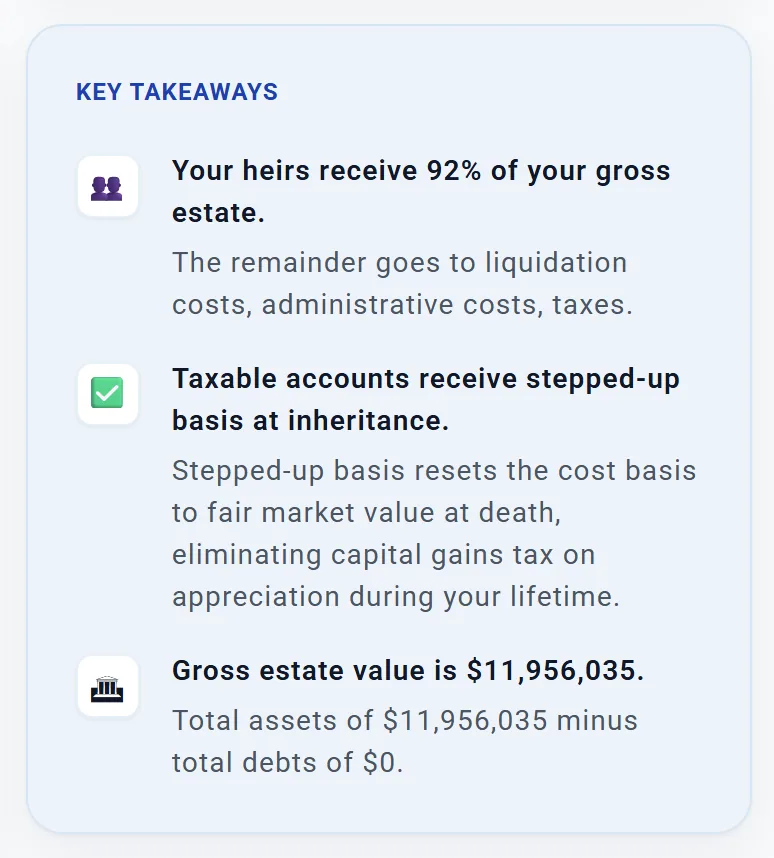
Key Takeaways, beside the ledger, sums up three points in words: the share your heirs receive and what the rest goes to, whether step-up applies, and the size of the estate.
Beneficiaries
At the bottom of the tab you can list who receives the estate and in what shares. The tab then splits Final Net Legacy between them. It changes no other figure.
- Choose Set Up Beneficiaries (Manage Beneficiaries once you have some).
- Choose Add Individual (a name, the relationship and a percent) or Add Organization (a name, a category such as Community Services, and a percent), then Add. Repeat for each, up to 15.
- Split Remaining Equally shares out what is not yet given.
- Choose Save. It closes only when the shares add up to exactly 100%.
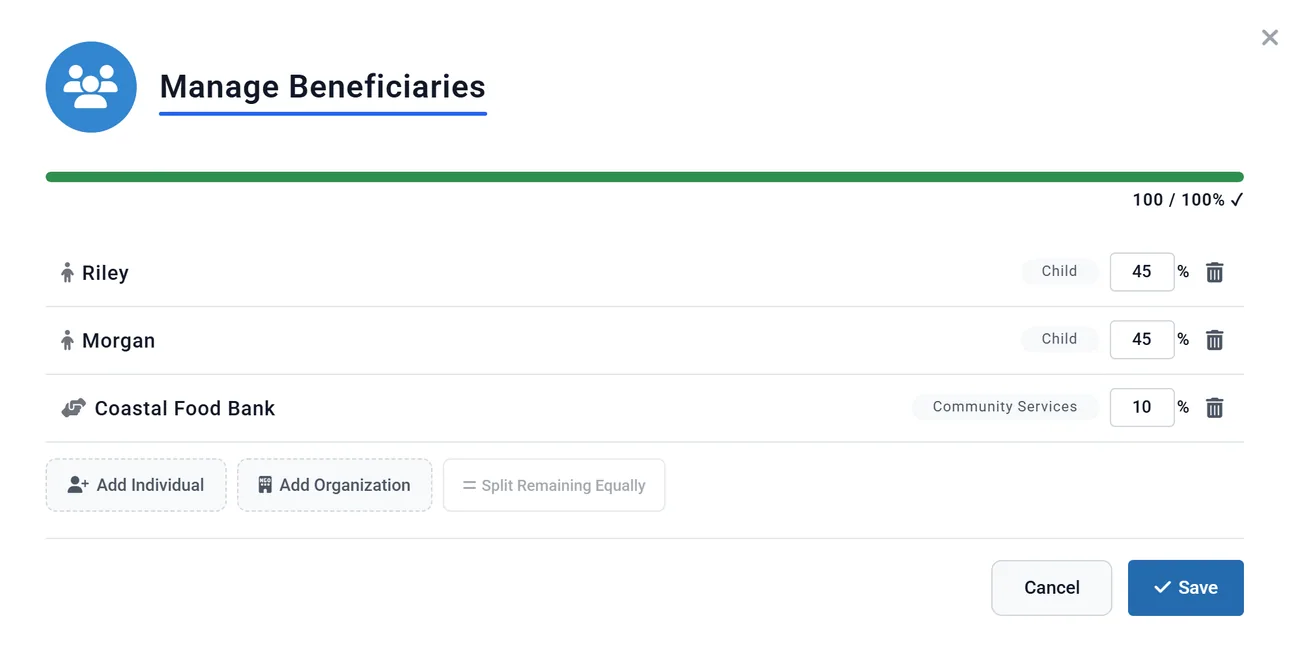
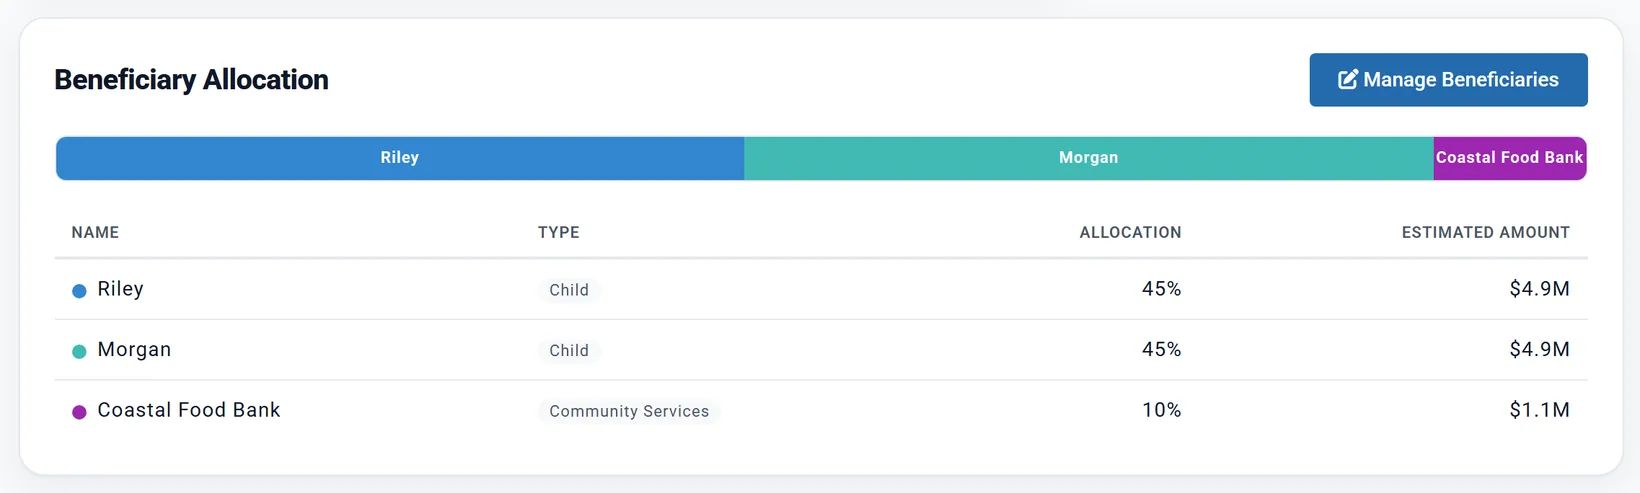
- Estimated Amount is the share of Final Net Legacy: 45% of $10,990,818 is $4.9M.
- An organization in this list gets a share of what is left after taxes. Charitable Giving in Scenario Parameters is different: it comes off before the taxes and lowers them.
- The flow chart ends in one band for each beneficiary instead of To Heirs.
What the Estate tab does not model
- Federal and state estate tax, and state inheritance tax.
- Your heirs' own tax brackets, and the years they take to empty an inherited IRA: one rate at the end instead.
- Probate and lawyers' fees beyond the Admin Costs rate.
- What passes at the first death: the tab shows the end of the plan, after both of you.
- Trusts, gifts made during your life (outside the UK panel), and who inherits which account: beneficiaries share the whole legacy.
- A Chance of Success range: the tab uses one projection.
The tab is an estimate. For a real estate plan, work with an estate planning attorney or a tax professional.
Canada and the UK
- Canada: the tab prices the death-year tax as one final return with Canada's own rules, and has no step-up switch. See At a death, and the Estate tab. Canada
- UK: the US rate inputs are hidden and a UK Inheritance Tax panel works out inheritance tax. See Inheritance tax on the Estate tab. UK
- Other countries start from the US rates and step-up, with a note to set them to how your country taxes an estate.
On a Preview account
The whole tab is blurred under "Unlock Your Full Retirement Plan". Planner+